Family site
Family site
Family site


Financial software fails differently than other software. A checkout bug loses a sale. A reconciliation bug loses trust, triggers an audit finding, or freezes customer funds.
That difference is why a vendor that builds excellent general software can still be the wrong choice for a lending platform, a payments backend, or a core-banking modernization. Strong engineering doesn't automatically come with transaction-processing discipline, reconciliation experience, or compliance fluency built in.
This guide compares 17 financial software development companies on five criteria: financial-domain depth, documented client work, security and compliance signals, delivery capability, and best-fit use case. The goal isn't a "best overall" ranking, because that ranking doesn't exist for financial software.
What you get instead is a shortlist built around your actual workload, whether that's lending, payments, wealth management, or core-banking modernization. Match your workload to that list, and the vendor you pick has already solved something close to your problem, not just something in the same industry.
Back to top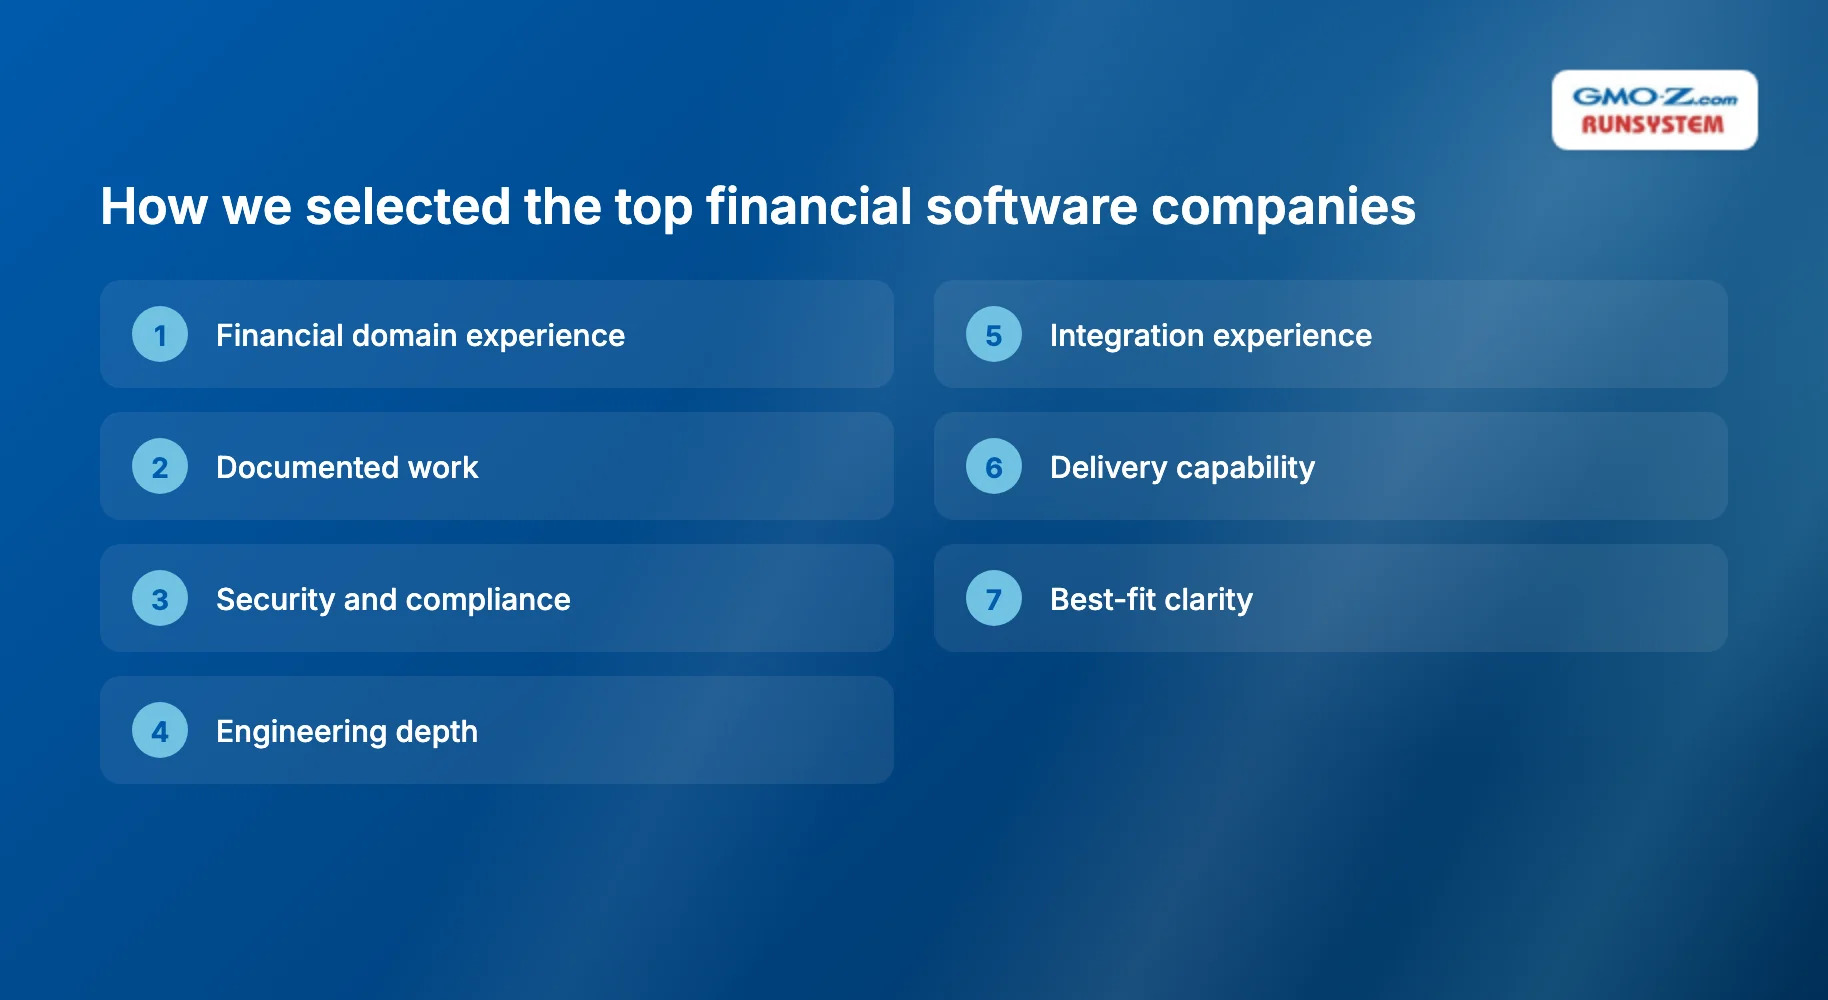
Vendors didn't make this list because they call themselves an "industry leader." They made it because they show verifiable financial-domain experience across seven areas.
Financial workflows differ from generic software in ways that matter operationally, not cosmetically. A payment retry that runs twice creates a duplicate transaction, not a rendering glitch. Domain experience in banking, lending, payments, insurance, or investment operations is the first filter here, not an afterthought bolted on at the end.
The table below summarizes what each evaluation area checks and why it matters for a financial buyer:
Evaluation area | What to look for | Why it matters |
Financial domain experience | Banking, lending, payments, insurance, investment, financial operations | Financial workflows differ significantly from generic software |
Documented work | Named clients, case studies, measurable outcomes | Validates claims beyond service-page copy |
Security and compliance | ISO 27001, SOC 2, PCI DSS, relevant regulatory experience | Financial applications handle sensitive data and transactions |
Engineering depth | Backend, cloud, data, APIs, transaction processing, QA | Reliability depends on more than UI development |
Integration experience | Core banking, payment processors, KYC, accounting, data providers | Financial systems rarely operate independently |
Delivery capability | Discovery through support and modernization | Matters for systems that stay in production for years |
Best-fit clarity | Project type, company size, region, engagement model | Prevents meaningless "best overall" rankings |
One editorial rule shapes every profile below: certification, regulatory experience, and compliance-support capability are not interchangeable, even though vendor marketing blurs them together constantly. An ISO 27001 certificate proves the vendor runs a formal information-security management system. That's it. It doesn't prove the vendor has built a PSD2 (the EU's Payment Services Directive) compliant open-banking flow, and it definitely doesn't mean the vendor has survived a PCI DSS audit for a card-issuing platform.
Regulatory experience is different: it means the vendor has actually delivered inside a specific regulatory framework, ideally more than once. Compliance-support capability is narrower still. It means the vendor can help you meet a requirement, nothing more. The vendor doesn't own the compliance outcome; that responsibility stays with you, the regulated entity.
Because those three things get blurred so often, read every certification claim in the profiles below against that distinction rather than treating it as a single "compliant or not" checkbox.
Back to topThe company you need depends on your financial workload, not on which vendor has the biggest logo wall. The table below gives a scan-friendly view of all 17; the profiles that follow go deeper on financial strength, evidence, and what to verify before signing.
Company | Best for | Financial strength | Delivery position |
GMO-Z.com RUNSYSTEM | BFSI transformation in APAC | Banking, lending, KYC, open banking, modernization | Large-scale Vietnam/APAC delivery |
EPAM | Enterprise financial transformation | Banking, capital markets, insurance | Global enterprise |
ScienceSoft | Complex financial and banking systems | Banking, payments, insurance | Enterprise / mid-market |
Forte Group | AI, data, and legacy modernization | Lending, insurance, wealth, financial operations | US-focused enterprise |
DataArt | Capital markets and financial data | Trading, institutional finance, analytics | Global |
Andersen | Payments and banking integrations | Wallets, payments, backend integration | Global delivery |
Itransition | Large financial platforms | Banking, lending, trading, RegTech | Enterprise |
Praxent | Digital banking customer experience | Lending, banking portals, UX | US financial institutions |
Baytech Consulting | US lending and custom financial applications | Lending, mortgage, enterprise apps | Boutique/onshore |
Algoscale | Financial data and AI | Analytics, fraud, data platforms | Data/AI-focused |
Kindgeek | Regulated fintech and neobanking | Payments, digital banking | Fintech specialist |
Django Stars | Lending and mortgage | Lending, mortgage, Python platforms | Specialist |
Itexus | Wealth and investment products | Trading, investment, digital banking | Fintech specialist |
Softjourn | Cards and payments | Prepaid, card processing, open banking | Payments specialist |
Velmie | Digital banking launches | Wallets, money transfer, white-label banking | Platform + development |
Vention | Scalable financial engineering teams | Lending, payments, wealth | Flexible global teams |
10Pearls | Digital banking and AI-enabled finance | Banking, payments, lending | Global product engineering |
GMO-Z.com RUNSYSTEM is best for banks, insurers, and lenders that need scalable engineering capacity for BFSI (banking, financial services, and insurance) transformation across APAC. The fit rests on financial-domain experience, not a general offshore rate card.
More than 20 years in the market, over 80 BFSI clients, and a work history that spans digital banking systems, loan origination platforms, and open banking integrations. It also covers KYC (know-your-customer identity verification) and eID solutions, banking CRM, document digitalization, and core system modernization alongside custom software development.
Its most cited financial deployment is SmartLoan, a loan and credit management system that Shinhan Bank deployed to manage its lending process. The platform's automated application review and interest-rate calculation cut errors and increased processing efficiency by roughly 30%, according to GMO-Z.com RUNSYSTEM. That's a concrete outcome, not a service-page claim. It names the client and quantifies the result.
Delivery runs through Vietnam-based engineering teams serving international clients. The company holds ISO 27001 (information security), ISO 9001 (quality management), and CMMI Level 3 (process maturity) certifications.
What sets it apart from a pure fintech product studio is the combination of financial-domain solutions plus offshore development capacity, rather than just one or the other. Before signing, confirm the exact scope of certification and prior experience against your specific jurisdiction and financial product; "BFSI experience" spans very different regulatory environments across APAC markets, so a generic claim isn't enough on its own.
EPAM fits large financial institutions that need global delivery capability across banking, capital markets, and insurance. It isn't built for a single-team engagement.
Eight of the world's ten largest investment banks work with EPAM. The firm serves more than 150 clients across capital markets alone, according to EPAM, and that scale shows up in its service range: cloud transformation, legacy modernization, data and AI, and the ability to run multiple transformation streams under one program.
Check whether the engagement size and pricing model still make sense if your program is smaller than the enterprise transformations EPAM is built around. A delivery organization sized for multi-year bank modernization can be overkill, and overpriced, for a single mid-complexity product.
ScienceSoft suits enterprises that want one full-cycle technology partner across banking, lending, payments, and insurance instead of assembling several specialist vendors.
Its financial work spans analytics and automation, security-focused engineering, and modernization and integration projects, built on decades of enterprise software delivery. That breadth is the appeal for a buyer who wants a single point of accountability across a multi-system program.
Ask for specific experience inside your exact financial vertical, whether that's claims processing, trading, or core banking. Broad enterprise-software experience doesn't always translate into deep familiarity with your workflow.
Forte Group fits financial institutions modernizing existing technology while layering in AI and data capabilities. It's not the choice for building a financial system from a blank slate.
The firm combines financial software engineering with data architecture, AI, legacy modernization, QA, and cloud, applied across lending, insurance, wealth management, and financial operations, and its engagements lean toward measurable outcomes rather than broad service menus.
Forte Group's strongest track record concentrates in US-centric financial-services engagements. Confirm relevant delivery experience if your program sits outside that market.
DataArt is the stronger fit for capital markets firms, investment managers, and technically demanding financial platforms. Not general-purpose banking apps.
Its work centers on trading platforms, institutional banking infrastructure, market and financial data, real-time analytics, and large-scale data pipelines, typically inside long-running enterprise engagements rather than short fixed-scope projects.
For capital markets work specifically, ask for the named delivery team and the specialists actually assigned to your account. Latency-sensitive trading infrastructure depends on individual engineer depth, not company-level case studies.
Andersen fits companies building integration-heavy payments or banking systems, where the hard problem is connecting to other people's infrastructure rather than designing a new product from scratch.
Its financial work covers payment-processing systems, digital wallets, backend financial infrastructure, and integrations with core banking and third-party providers, and it can scale engineering teams as integration scope grows.
Confirm regulatory expertise for your specific target country. General financial-industry experience doesn't guarantee familiarity with, say, a particular market's open banking mandate or card-scheme rules.
Itransition suits enterprise programs that need broad technical capability under a single vendor. Its scope spans core banking, lending, trading, and RegTech (software built specifically for regulatory compliance and reporting), not one narrow specialty.
Its financial portfolio also includes BI/data work and legacy modernization. That positions it as a generalist enterprise vendor with financial-sector depth rather than a boutique specialist.
Check whether a large delivery organization matches your required speed and governance model, because enterprise vendors built for multi-year programs sometimes move slower than a smaller team would on a tightly scoped project.
Praxent is the right call when your backend financial infrastructure works but your customer-facing experience does not. You need that front end modernized without breaking what already runs underneath.
The firm focuses on digital banking portals, account onboarding, lending workflows, and wealth and financial customer experiences, and its typical client is a traditional financial institution integrating a modern front end onto existing banking infrastructure.
Praxent's core strength is the interface and workflow layer. If the project expands beyond that into backend financial engineering, confirm its depth there specifically.
Baytech Consulting fits US organizations that want close, onshore collaboration on lending and custom financial applications rather than an offshore delivery model.
Its work spans mortgage and lending platforms, custom financial applications, enterprise software, and cloud and AI integration, delivered through an onshore team structure.
Scale is the thing to check. An onshore, closely collaborative model built for focused engagements may not have the bench depth for a very large, multi-team transformation program.
Algoscale is the better fit when your core problem is financial data, analytics, or AI, not end-user application design. Treat it as a data specialist working inside finance, not a generalist fintech agency.
Its differentiated strength covers financial data platforms, data engineering, analytics and BI, fraud and risk use cases, AI/ML, and cloud infrastructure built to support those workloads.
Ask for evidence from production financial systems comparable to your proposed project, specifically around data volume and regulatory sensitivity, since data-platform work in finance carries different governance requirements than analytics in other industries.
Kindgeek suits fintech businesses building regulated consumer financial products, where security and compliance credentials matter as much as feature velocity.
Its work covers neobanking, payments, wallets, lending, and financial product engineering, built around the credentials relevant to delivering a regulated product rather than a general software project.
Check fit for large legacy transformation versus greenfield financial products. A team built for launching new regulated fintech products isn't automatically suited to modernizing a decade-old core system.
Django Stars fits lending and mortgage businesses already committed to the Python ecosystem, pairing financial-workflow experience with deep Python/Django expertise.
Its focus areas include lending, mortgages, complex financial workflows, and long-term financial platform development, concentrated specifically in that technology stack.
A specialist this focused earns that focus by not spreading equally across every financial category. Confirm fit if your project sits outside lending and mortgage.
Itexus fits startups and growth-stage financial companies building customer-facing wealth, trading, or investment products, where speed to market matters alongside financial accuracy.
Its portfolio spans wealth management, trading applications, investment platforms, digital banking, payments, and financial mobile products.
Watch for enterprise-scale operational requirements. Larger vendors typically carry more infrastructure depth for high-volume, mission-critical operations than a growth-stage specialist is built to support.
Softjourn is the tightest specialist fit when payments or cards sit at the center of your product, not a peripheral feature.
The firm has delivered more than 150 fintech projects since 2001, according to Softjourn, concentrated in card processing, prepaid products, payment systems, expense management, and open banking. For PayPartners, one documented example, Softjourn built prepaid card processing that let employers issue payment cards to overseas employees, with interfaces to track employee spending.
Softjourn's specialization is the asset here. It's also the boundary, so check fit if your primary problem is lending, insurance, or capital markets instead.
Velmie is the right choice when time-to-market matters more than building every banking component from zero.
Its white-label banking platform covers wallets, money transfer, and core banking infrastructure, deployed on AWS/cloud with customization around prebuilt financial components. Clients can send payments to more than 150 countries in over 75 currencies through Velmie's partner network, and the platform is built to launch products in roughly three months on average, according to Velmie.
Prebuilt components accelerate launch. But confirm customization limits and long-term portability before committing, because moving off a white-label platform later is a bigger decision than choosing it now.
Vention fits organizations that already have internal technical leadership and need additional financial engineering capacity, not a vendor to own the architecture decisions.
It supplies flexible development teams covering payments, lending, wealth management, cloud, AI/ML, and QA, structured to plug into an existing technical organization rather than replace it.
Check the depth of domain expertise within the specific engineers assigned to your account. A staff-augmentation model is only as strong as the individuals staffed, not the company's aggregate experience.
10Pearls suits organizations that want a full-cycle product team combining engineering, UX, and emerging technology under one roof, rather than coordinating separate vendors for design and development.
Its financial work spans digital banking, payments, lending, mobile applications, AI/ML, and product design and QA, positioned as end-to-end product engineering rather than a pure staffing model.
Confirm exact domain experience relevant to your required financial workflow. Broad product-engineering capability doesn't guarantee deep prior exposure to your specific financial process.
Back to top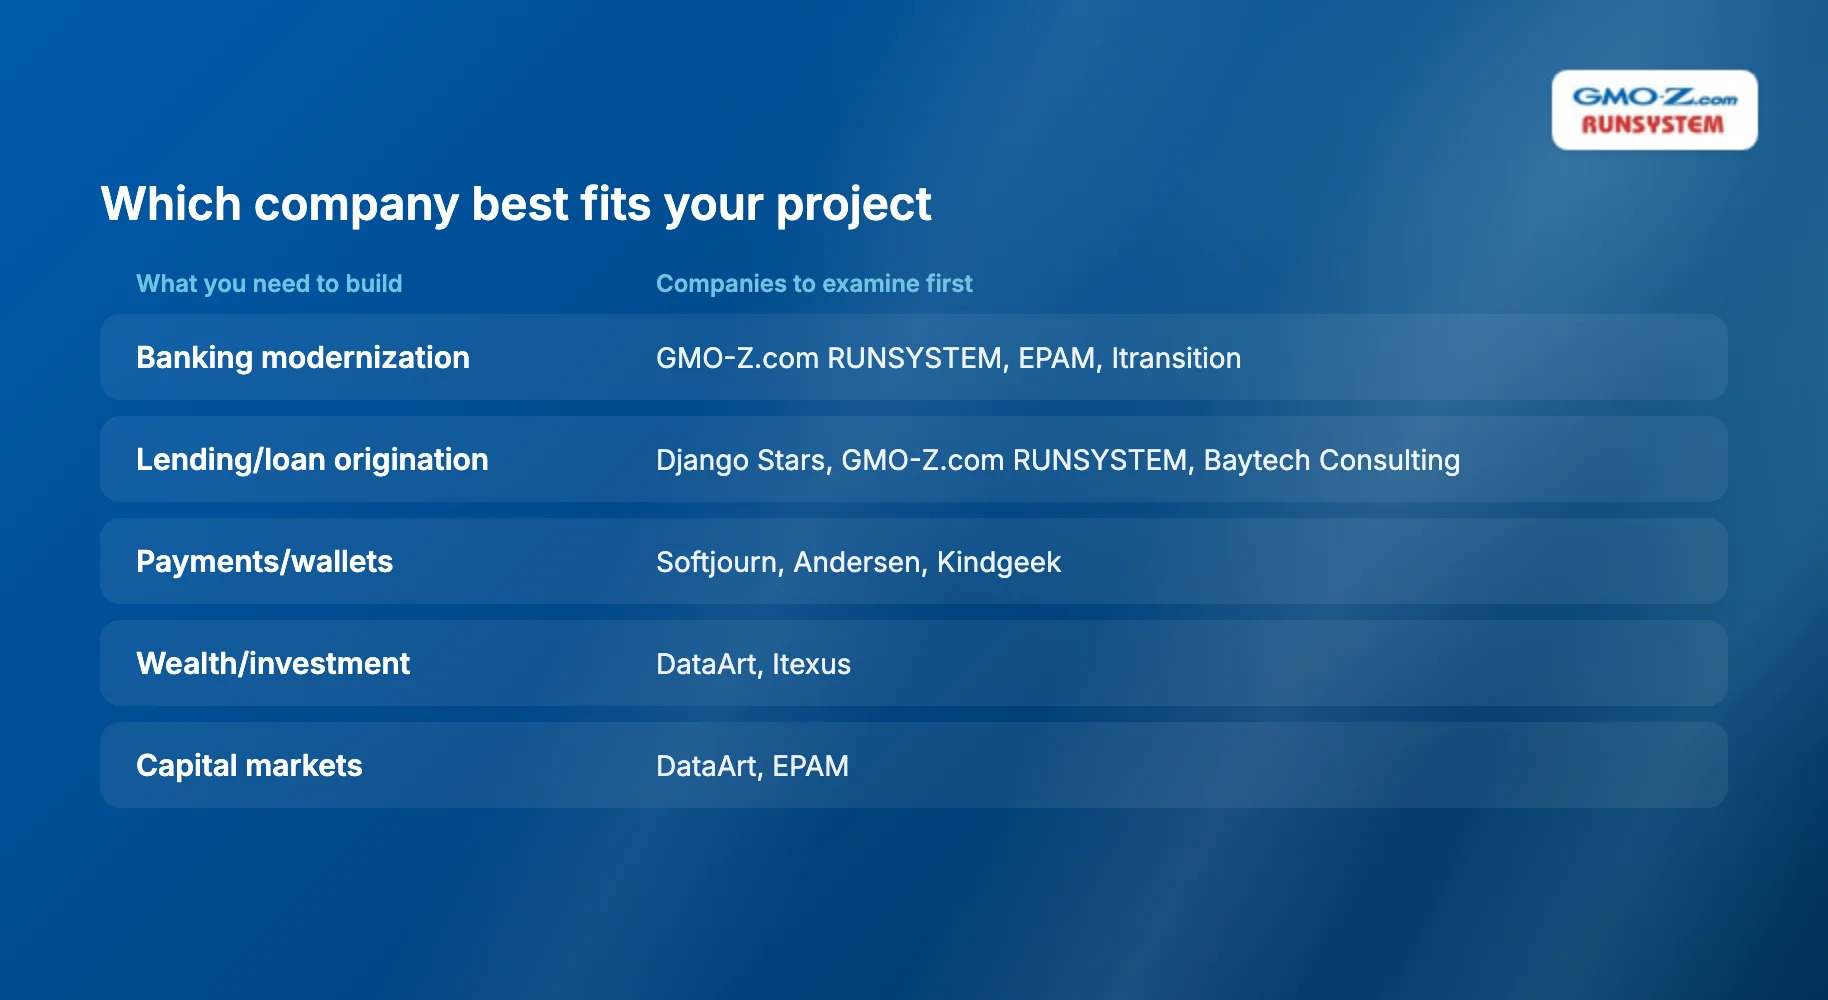
Shortlist by financial workload first, vendor name second. That single rule prevents the most common vendor-selection mistake, which is picking a name recognized from a conference sponsorship instead of a company that has actually solved a problem shaped like yours.
The matrix below maps common financial workloads to the capabilities that matter most and the companies worth examining first for each:
What you need to build | Capabilities to prioritize | Companies to examine first |
Banking modernization | Legacy integration, cloud, migration, financial workflows | GMO-Z.com RUNSYSTEM, EPAM, Itransition |
Digital banking/neobank | Core banking integration, KYC, payments, mobile | Kindgeek, Velmie, GMO-Z.com RUNSYSTEM |
Lending/loan origination | Underwriting, servicing, credit workflows | Django Stars, GMO-Z.com RUNSYSTEM, Baytech Consulting |
Payments/wallets | Transaction reliability, reconciliation, PCI expertise | Softjourn, Andersen, Kindgeek |
Wealth/investment | Financial data, portfolio logic, trading UX | DataArt, Itexus |
Capital markets | Low latency, data pipelines, trading infrastructure | DataArt, EPAM |
Financial data/AI | Data engineering, model governance, analytics | Algoscale, Forte Group |
Customer-facing banking UX | Product design plus legacy integration | Praxent, 10Pearls |
Rapid digital-bank launch | Prebuilt banking infrastructure | Velmie |
APAC financial transformation | BFSI experience plus scalable regional delivery | GMO-Z.com RUNSYSTEM |
Don't shortlist a vendor simply because "fintech" appears in its service menu. That phrase shows up on almost every enterprise software firm's homepage now, and it says nothing about whether the vendor has handled your specific workload.
A company with five relevant lending implementations is frequently a safer choice for a lender than a much larger consultancy with 200 unrelated finance projects, because those 200 projects might span insurance, payments, and wealth management and never once touch lending. Depth in your workload beats breadth across the category.
Back to topDecide the engagement model before comparing vendors. The same company can be the right or wrong choice depending on which model you pick.
Full outsourcing means the vendor owns delivery end-to-end. It fits when you lack capacity for day-to-day technical direction, but you're also trusting the vendor's judgment on architecture decisions you won't see coming.
A dedicated team works under your architectural direction while the vendor handles staffing, which fits when you have technical leadership in-house but need more hands. It still requires you to stay engaged in daily oversight.
Staff augmentation adds individual engineers into a team you already run. It fits narrow capacity gaps. But it puts the full burden of financial-domain knowledge transfer on your side, since the vendor supplies people, not process.
Define the financial workflow before comparing frameworks: lending, payments, insurance, wealth, banking, trading, or internal financial operations. Each one carries different reliability and compliance demands.
Domain similarity matters more than React versus Angular. A vendor fluent in payment reconciliation but unfamiliar with your framework will ramp up faster than one fluent in your framework but unfamiliar with reconciliation logic, because the framework is learnable in weeks and reconciliation logic usually isn't.
Then ask every shortlisted vendor to show that workflow already running in production, not in a pilot. Request evidence of comparable transaction volumes, integration complexity, regulatory constraints, and measured outcomes. A vendor that can't produce this is asking you to be its first real financial client, whether it says so or not.
Reject a vague answer like "we understand financial compliance." That sentence tells you nothing.
Ask instead about direct experience with the requirements that apply to your project specifically:
Ask how the team handles the failure modes that are specific to financial systems, not general software failures.
Push for a real answer on idempotency (preventing a retried request from processing the same payment twice), duplicate-transaction handling, failed-payment recovery, reconciliation, audit trails, disaster recovery, high availability, and third-party API (the interface that lets two systems exchange data) failures. A vendor that answers these clearly, with a real mechanism rather than "we handle that," has actually built financial systems before. One that can't name a mechanism hasn't.
Verify who will actually do the work, not who appears on the sales call. Check seniority, financial-domain experience, whether an architect stays involved past kickoff, dedicated QA and security roles, staff turnover history, and whether subcontractors will touch your codebase.
Confirm the exit terms before you need them, not after. Source-code ownership, documentation standards, IP assignment, cloud account ownership, knowledge transfer, and the handover process all belong in the contract, explicitly, not as something assumed.
Weigh these criteria together rather than picking on a single factor:
Financial vendor score = domain fit (30%) + security and compliance (25%) + engineering evidence (20%) + delivery fit (15%) + commercial fit (10%)
Back to topFinancial software costs more than comparable general software because compliance, integration complexity, and reliability engineering add work that a standard CRUD application never needs, and the range widens further as transaction volume and regulatory scope increase.
Regional hourly rates explain part of that gap. North American vendors typically run 200 an hour, Western European vendors 150, Eastern European vendors 45, based on current market surveys.
Those rate bands say less than they seem to. A focused MVP (minimum viable product, the smallest working version worth shipping) or internal financial tool with limited integrations sits at the low end of typical project budgets. A mid-complexity financial product with multiple user roles, external APIs, and security or compliance requirements costs substantially more.
An enterprise financial platform handling high transaction volume, multiple integrations, and legacy migration moves into custom, multi-phase pricing territory entirely. A core-modernization or capital-markets platform almost always needs a mission-critical architecture engagement scoped on its own terms, not a rate card.
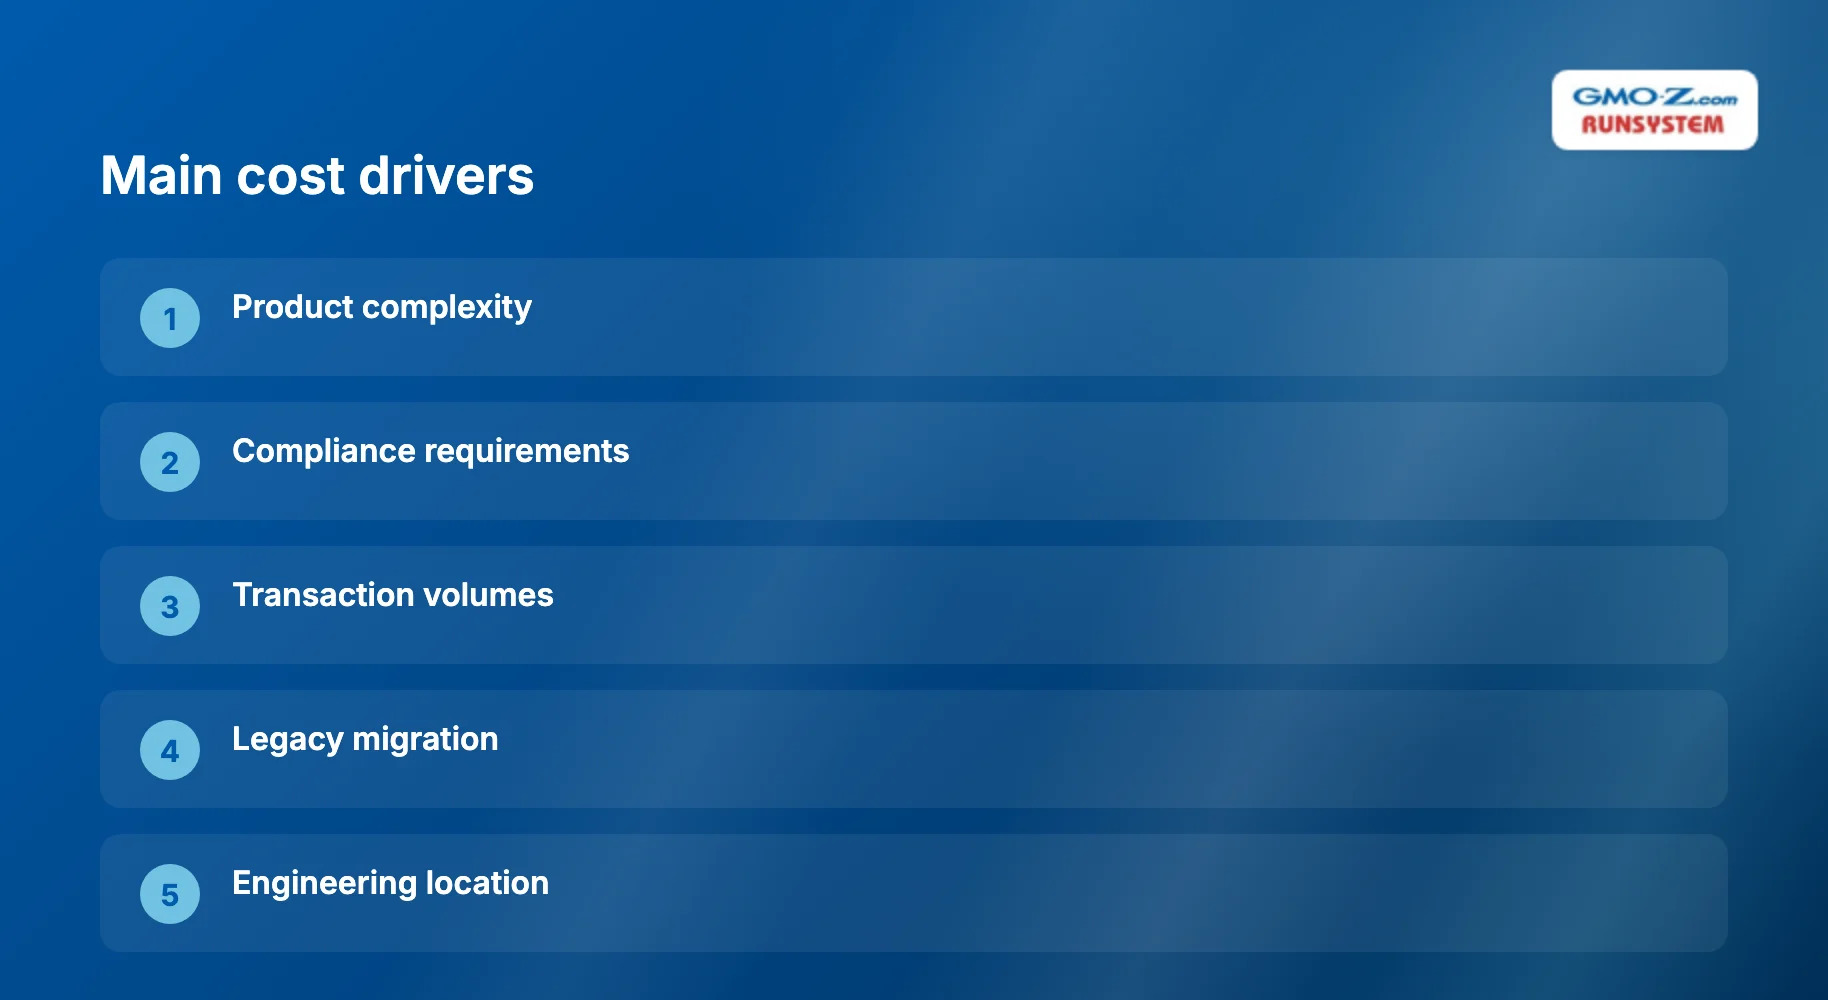
Several factors push financial software costs up independent of hourly rate:
The real comparison point is total cost of ownership, not the headline rate:
TCO = development + integration + compliance + infrastructure + maintenance + change cost + exit cost
A lower hourly rate can produce a higher TCO. A vendor that ships fast at a cheap rate but leaves you with poor architecture, thin documentation, or expensive vendor lock-in will cost more in the end, just later and in a different line item.
Add the rework, delay, and exit costs, and that "cheap" vendor often runs higher in total than the alternative. The vendor that charged more but delivered a system you can actually maintain and extend ends up cheaper. It just doesn't look that way on the invoice.
Back to topThe organizations that get financial software right treat vendor selection as matching a specific workload to specific proof, not as picking the biggest name on a shortlist. Lending, payments, wealth management, and capital markets each demand different reliability engineering and different compliance fluency. No single company excels equally at all of them, no matter what the homepage says.
Use the workload-to-capability matrix above to build your first shortlist. Then run every candidate through the reliability-engineering and compliance questions in the "how to choose" section before any commercial conversation starts.
A vendor that answers those questions concretely, with named mechanisms and production evidence, has earned a seat at the table. One that answers in generalities hasn't, regardless of company size.
If your workload is BFSI transformation across APAC, that verification step matters even more. It separates a vendor that has actually run your kind of system in production from one that only says it has.
Banking modernization, lending platforms, and open banking integrations each surface failure modes that only show up at real transaction volume. The vendor you pick needs to have already hit those failure modes and recovered from them.
GMO-Z.com RUNSYSTEM's track record with institutions like Shinhan Bank is worth examining against that bar, on your workload specifically, not on certification alone. Scope and engagement terms vary per project; contact RunSystem for a quote.
Back to topA focused MVP with limited integrations typically takes 3 to 6 months. A mid-complexity product with compliance and multiple integrations runs 6 to 12 months. An enterprise platform with legacy migration or high transaction volume often takes 12 to 24 months across phased delivery.
Yes, if the new vendor can review existing source code, documentation, and architecture before committing to a timeline. Ask for a discovery phase first; a vendor that quotes a handover cost without reviewing the actual codebase is guessing, not scoping.
Ownership depends entirely on the contract, not on default assumption. Most enterprise engagements assign full IP and source-code ownership to the client, but confirm this explicitly in writing before signing, including for any third-party libraries used.
Not necessarily, but regulatory and time-zone fit matter more than physical location. A partner with proven experience in your jurisdiction's compliance requirements and enough overlap hours for real-time collaboration can work effectively from another region.
Prepare your financial workflow type, expected transaction volume, required integrations, applicable compliance frameworks, and current system documentation if one exists. That preparation lets a vendor scope accurately instead of quoting a generic estimate.
Back to top